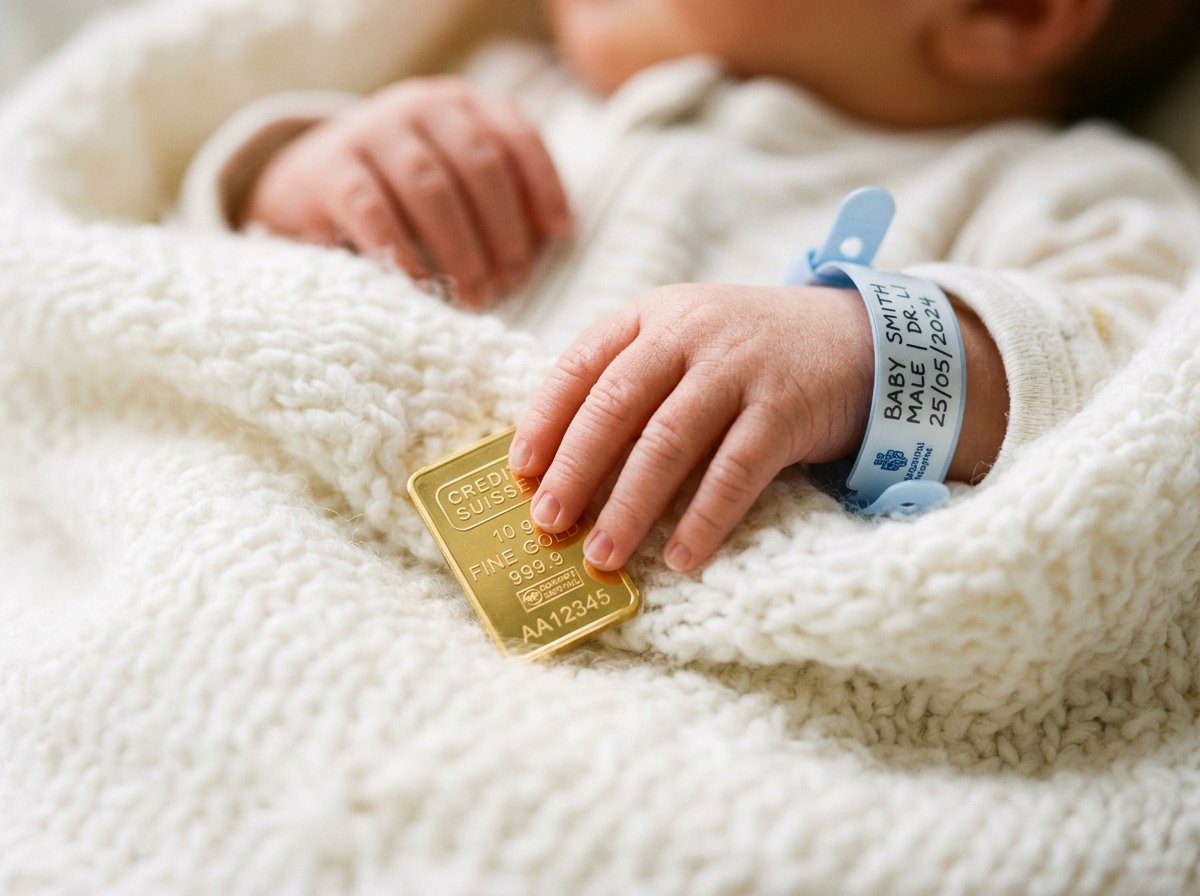
In Canada, building six- or seven-figure financial security for your child before their 20s does not require winning a lottery or receiving an inheritance; it is the mathematical outcome of combining uninterrupted compound growth from an early age with regulated instruments: Permanent Life Insurance (Universal Life or Whole Life) and the Registered Education Savings Plan (RESP).
Most Canadian families make the costly mistake of waiting until their children turn 18 or 20 before addressing long-term wealth building. By then, they have missed out on two crucial decades of exponential compounding, and insurance underwriting costs can be up to five times higher. In the Canadian insurance industry, once a newborn reaches 15 days of age, parents can officially initiate the permanent life insurance application. Taking advantage of this early window is Canada's most effective generational wealth strategy.
1. The Physics of Money: Why Age Zero is Your Ultimate Advantage
Albert Einstein famously described compound interest as the eighth wonder of the world: «He who understands it, earns it; he who doesn't, pays it.» In Canadian wealth planning, the scarcest asset is never initial capital—it is uninterrupted compounding time.
Under the Rule of 72, dividing 72 by the annual expected growth rate reveals how many years it takes for capital to double. At a conservative 7.2% return, money doubles every 10 years. If you start at age 0:
- At age 10, funds have doubled once.
- At age 20, funds have doubled twice (4x).
- At age 30, funds have doubled three times (8x).
- At age 50, that initial growth base has multiplied 32 times without adding another penny.
Waiting until age 25 forfeits the first three doublings, requiring nearly ten times the monthly contribution to reach the same milestone.
2. The 3 Regulated Canadian Tools for Early Child Wealth
To establish an enduring generational foundation, in Carlos D. Castillo's financial practice and under Canadian regulatory standards, we structure child wealth across three complementary pillars:
🏛️ The Canadian Early Wealth Triad:
1. Permanent Life Insurance (Universal Life or Whole Life): Lifetime medical insurability protection + tax-sheltered Cash Value growth.
2. RESP (Registered Education Savings Plan): Up to $7,200 CAD in free federal government grant money (CESG) dedicated to post-secondary education.
3. TFSA Transition at Age 18: Reallocating accumulated gains into the Tax-Free Savings Account upon reaching legal age in Alberta.
3. Permanent Life Insurance: The Early Head Start Advantage (Universal Life and Whole Life)
Parents often ask: «Why insure a newborn if they have no dependents or wages to replace?» The answer is simple: permanent child insurance is an asset accumulation and wealth transfer strategy, not just death benefit protection.
Offered by Canada's leading tier-one insurers (Canada Life, Manulife, Sun Life, Equitable), permanent insurance options (such as Universal Life or Whole Life) deliver three decisive benefits:
- Guaranteed Lifetime Insurability: By securing a policy once the baby is 15 days old while completely healthy, they remain protected for life. If your child develops medical conditions later in youth (asthma, juvenile diabetes, heart irregularities), commercial underwriting can never cancel or rate coverage. Future guaranteed insurability riders can also be added.
- Paid-Up Policies (10 or 20-Pay): You can fund the policy so it is completely paid off by age 10 or 20. Your child will never owe another monthly premium in their adult life.
- Tax-Sheltered Cash Value: Cash equity compounds inside the policy tax-exempt under Section 148 of the Canadian Income Tax Act (via investment accounts in Universal Life or dividends in participating Whole Life). By age 20 to 25, the young adult can collateralize or access funds for a home down payment in Calgary or Edmonton while maintaining coverage.
Federal CRA Framework: Canadian exempt permanent life insurance policies permit tax-sheltered growth within prescribed limits. Review official federal guidelines at canada.ca/revenue-agency.
4. Comparison: Bank Savings vs. Comprehensive Child Strategy
| Financial Metric | Traditional Bank Savings | Comprehensive Strategy (Permanent Insurance + RESP) |
|---|---|---|
| Average Annual Growth | 0.5% – 1.5% (Loses against inflation) | Competitive historical growth (investment returns in Universal Life or dividends in Whole Life) + 20% federal grant |
| Tax Impact (CRA) | Taxable annual interest (T5 slips) | Tax-deferred and tax-sheltered compound growth |
| Federal Government Grants | $0 CAD | Up to $7,200 CAD in free education funding (CESG) |
| Lifetime Health Coverage | None | Guaranteed permanent coverage starting at 15 days of age |
| Capital Access at Age 20 | Only what wasn't spent | Liquid equity for property, tuition, or enterprise |
5. Real Case Simulation: A Calgary Family at $200 CAD/Month
📊 Practical Case: The Martinez Family in Calgary, Alberta
When their son Mateo reached 15 days of age, his parents redirected $200 CAD per month ($100 to Permanent Life Insurance —Universal Life or Whole Life— and $100 to an RESP):
• At Age 18 (Post-Secondary): The RESP has over $42,000 CAD available, bolstered by compounding and $7,200 in federal grant funding. Mateo enters higher education debt-free.
• At Age 20 (Policy Paid Off): The permanent life policy is 100% paid up. Mateo owns over $350,000 CAD in permanent insurance coverage and a rapidly expanding cash equity reserve.
• At Age 50 (Generational Legacy): Without adding another single dollar since age 20, the policy's cumulative value exceeds $850,000 CAD due to five decades of tax-sheltered compounding.
6. 3 Critical Mistakes to Avoid
- Relying on standard youth savings accounts: Bank accounts paying under 1.5% ensure inflation erodes over 40% of purchasing power over 18 years.
- Waiting until adulthood to secure insurance: Health changes cannot be predicted. Any diagnosis in adolescence can permanently lock out affordable coverage.
- Neglecting free government RESP grants: Thousands of families miss out on up to $7,200 CAD in matching federal grants due to lack of planning.
7. Frequently Asked Questions
Carlos D. Castillo
Financial Security Advisor with over 30 years of international wealth planning experience and more than a decade serving families and entrepreneurs across Alberta and Canada. Independent representative associated with Greatway Financial. Dedicated to financial literacy and generational wealth building.
Compliance Disclaimer: This article is published for educational and informational purposes only and does not constitute customized legal, financial, or tax advice. Historical policy dividend rates or investment returns do not guarantee future performance. Dividends within participating whole life policies depend upon the operational performance of regulated Canadian insurance carriers. RESP grants are governed by Government of Canada eligibility criteria. Always consult a licensed provincial Financial Security Advisor before initiating any policy. Carlos D. Castillo operates under the supervision of Greatway Financial MGA.